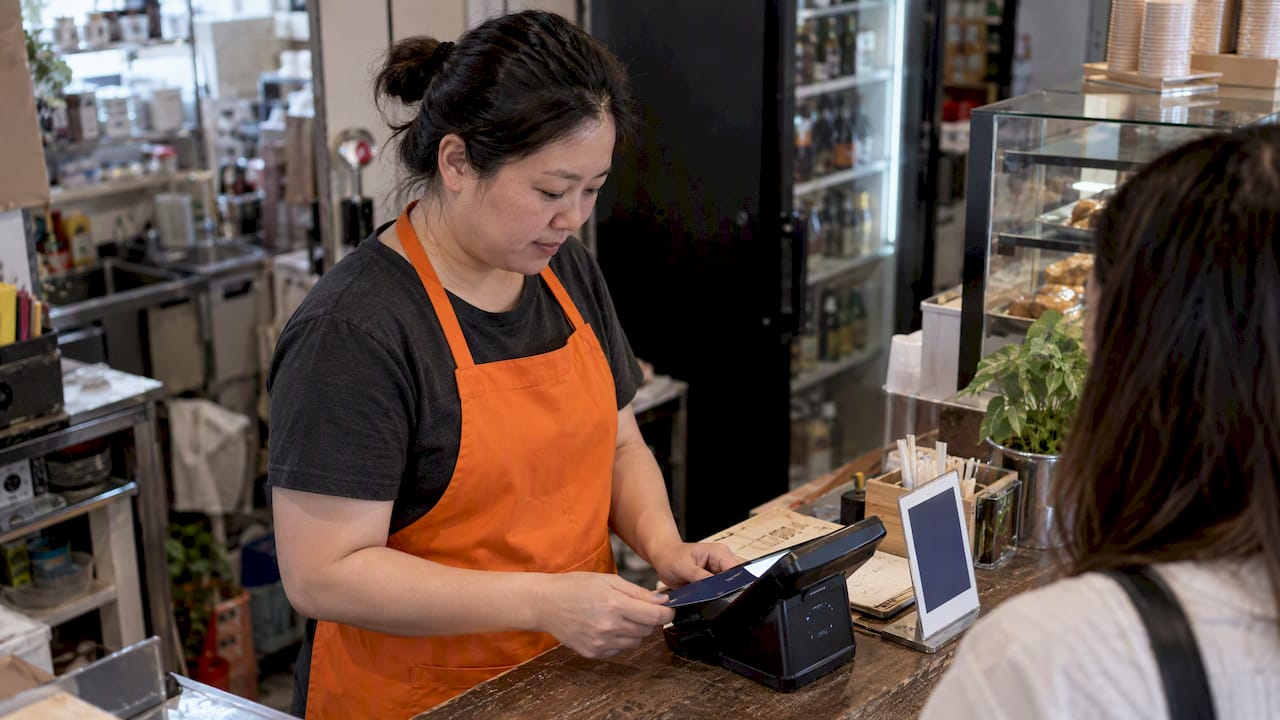
For most Singapore retail and omnichannel SMEs, an integrated POS and payments workflow beats bolting a pure payment gateway onto a separate till system. It cuts reconciliation work, keeps PayNow and card transactions in one view, and still runs on MAS-regulated rails. This guide walks through the fees, local payment methods, and vendor questions that actually decide the comparison between Stripe and HitPay, and where a tailored POS fits better than either.
TL;DR:
- Compare percentage and fixed fees, refunds, chargebacks, international card charges, and monthly or terminal costs against your actual ticket size and payment mix.
- PayNow and QR often cost less than cards, but savings depend on your payment mix and ticket size, so request a quote using sales figures.
- Stripe suits online businesses with technical capacity and API needs; HitPay serves APAC merchants seeking bundled payments, invoicing, and point of sale.
- Before committing, test hosted checkout, webhook coverage for refunds and disputes, existing platform plugins, and sandbox access; documentation quality can signal integration effort.
- Get written settlement windows and reserve triggers for each payment rail, then verify the contracting entity’s current MAS authorization in the Financial Institutions Directory.
Table of Contents
- Stripe, HitPay and the categories they actually belong to
- What fees actually move the needle in Singapore
- Which payment rails matter to Singapore customers
- Checking the integrations and developer tools you’ll actually use
- How settlement timing affects your cashflow
- Choosing terminals, Tap-to-Phone or an integrated POS
- How to choose: a checklist before you sign anything
- Where a tailored POS beats a generic payment gateway
- See how POSFlow handles a sale from product to payment
- FAQ
- Sources
Stripe, HitPay and the categories they actually belong to
“Stripe vs HitPay” sounds like a straight fight, but the two sit in different categories, and a third category often fits Singapore SMEs better than either.
Stripe is a global payment processor built for developers. It gives you deep API control, strong documentation, and the flexibility to build almost any checkout flow, but you carry more of the integration work yourself or pay someone to do it. HitPay is a Singapore-headquartered, full-stack payments platform aimed squarely at APAC merchants, bundling e-commerce, point of sale and invoicing into one account, with claimed adoption past 15,000 merchants.
The third category is a POS-first solution where payments, inventory and accounting are designed around your actual shop floor or counter workflow, rather than around an API you have to wire up yourself.
- Global processors (Stripe) suit businesses selling mainly online, often across borders, with in-house technical capacity or a developer on retainer.
- Full-stack regional platforms (HitPay) suit omnichannel SMEs that want cards, PayNow and QR under one dashboard without heavy engineering.
- POS-first platforms suit retail, F&B and service businesses where the till, stock count and daily reconciliation matter more than custom checkout logic.
Pricing follows the same split: processors charge per transaction with few bundled extras, full-stack platforms bundle POS and online payments into one fee structure, and POS-first tools price around the operational workflow rather than just the payment rail.
What fees actually move the needle in Singapore
Before comparing quotes, line up the fees on the same basis. Most Singapore merchants end up comparing six cost lines, not one headline rate.
- Percentage fee per transaction, usually the biggest line item and the one quoted most prominently.
- Fixed fee per transaction, often small but material at low ticket sizes.
- Refund handling, where some providers still charge the original processing fee even when you return the money.
- Chargeback fees, charged when a cardholder disputes a payment, regardless of outcome in some cases.
- Cross-border or FX fees, triggered when a customer’s card is issued outside Singapore.
- Monthly, terminal rental or subscription fees, which can outweigh the percentage rate for low-volume merchants.
At a typical card rate plus a small fixed fee, card payments alone can run into several hundred dollars a month, before refunds or chargebacks are counted. Shift more volume to PayNow and QR, which commonly carry lower or flat fees, and a given turnover can cost noticeably less to process. The arithmetic only works if you know your own ticket size and payment mix first.
Average ticket size and payment mix are the two inputs that swing your monthly fee the most, according to payment gateway selection guidance. Get a quote based on your real numbers, not a generic rate card, before you sign anything.
Which payment rails matter to Singapore customers
Singapore shoppers expect to pay however suits them at that moment, and the rails you support directly affect whether they complete the sale.
- PayNow and NETS QR are the default low-friction option for many local customers, often settling faster and at a lower cost than cards.
- E-wallets such as the major mobile wallet apps cover customers who prefer tap-and-scan over typing card details.
- Domestic cards issued by Singapore banks typically process more cheaply than international cards.
- International cards are essential for tourist footfall and cross-border e-commerce but usually carry FX and cross-border fees.
- B2B payment methods, including invoicing and bank transfer, matter if you sell to other businesses rather than consumers.
Running all of these through one dashboard, rather than reconciling a card terminal against a separate QR app and a separate online gateway, is where a unified system earns its keep. Each rail can carry a different fee and settlement timeline, so a provider that reports them all in one ledger saves real bookkeeping hours.
Pro Tip: Ask any vendor to show you a single day’s reconciliation report covering cards, PayNow and QR together, not three separate exports you have to merge yourself.

Checking the integrations and developer tools you’ll actually use
A demo looks polished regardless of how much engineering work sits behind it, so the checklist matters more than the sales pitch.
- Confirm whether hosted checkout is available out of the box, or whether you need a developer to build the payment page.
- Ask to see webhook coverage, specifically for refunds, disputes and settlement events, not just successful payments.
- Check plugin availability for the e-commerce platform and accounting package you already use, rather than assuming compatibility.
- Request access to a sandbox environment so your own team, or whoever builds for you, can test real flows before going live.
- Look at sample code and documentation quality, since thin docs usually predict a slow, expensive integration later.
Good vendor selection in payments means verifying these technical signals in a live demo, not taking a features page at face value. If your accounting runs through InvoiceNow-compliant software, our inventory and accounting integration guide walks through what to check before you commit.
How settlement timing affects your cashflow
Payout cadence is easy to overlook until it becomes a cashflow problem. Card settlements commonly land a few business days after the sale, while PayNow and QR transactions often settle faster, sometimes close to instant.
- Ask exactly how many business days separate a sale from the money hitting your bank account, for each rail you plan to use.
- Understand reserve or hold policies: some providers hold back a percentage of volume, especially for new accounts or certain industries, until a track record is established.
- Clarify what triggers a hold, such as a spike in refund rate or an unusually large transaction.
- Check how multi-currency receipts are converted and reported, since this affects both your bank reconciliation and your accounting entries.
A slower payout schedule is manageable if you plan for it. An unexpected reserve on a bad week is not, so ask before you sign rather than after a hold hits your balance.
Choosing terminals, Tap-to-Phone or an integrated POS
If you also sell in person, hardware choices carry their own trade-offs.
- Rented terminals keep upfront cost low but add a recurring monthly line and tie you to one provider’s hardware refresh cycle.
- Owned terminals cost more upfront but remove the rental fee over time.
- Tap-to-Phone, which turns a compatible smartphone into a card reader, suits pop-ups and mobile selling where a fixed counter terminal does not fit.
Whichever you choose, confirm that card payments sync automatically with your inventory count and accounting ledger rather than needing manual entry at the end of the day, and ask what the support SLA covers if a terminal fails during trading hours, and consider expert help for Shopify accessibility and data privacy compliance.
How to choose: a checklist before you sign anything
Run any shortlisted provider, Stripe, HitPay or a POS-first alternative, through the same checklist so quotes are comparable.
- List your fee lines: percentage rate, fixed fee, refund policy, chargeback cost, FX fee, and any monthly or rental charge.
- Confirm rail coverage: PayNow, NETS QR, major wallets, domestic and international cards, and B2B transfer if relevant.
- Verify MAS licensing: check the MAS Financial Institutions Directory entry for the legal entity you would be contracting with, and confirm it is authorised for merchant acquiring. Stripe’s Singapore entity holds an active Major Payment Institution licence covering account issuance and cross-border transfers, and HitPay’s Singapore entity is also listed with active MPI status.
- Test the integration in a sandbox before committing engineering time or budget to a build.
- Ask about settlement timing and reserves in writing, not verbally in a sales call.
- Check support channels and response times, especially for payment failures during business hours.
Good answers are specific: a named settlement window in business days, a documented reserve policy, a sandbox you can log into today. Vague answers, like “settlement is usually quick”, are a sign to ask again or walk away.
Pro Tip: If you’re spending more time reconciling payment rails than selling, the problem is usually the workflow around the payment, not the payment rate itself.
Broadly, the decision comes down to two paths: a low-effort, bundled route that trades some flexibility for speed of setup, or a high-flexibility API route that takes longer to build but can be shaped exactly to your process. If budget is a factor in the build, our PSG eligibility guide is worth checking before you scope either path.
Where a tailored POS beats a generic payment gateway
As an app development team based in Singapore, we’ve often seen SMEs pick a payment provider first and only discover the reconciliation challenges afterwards. Our starting point is the opposite: look at the workflow, then recommend the simplest suitable solution, whether that’s a ready product, an adapted one, or a custom build.
We provide app fit reviews to help work out the most cost-conscious route before any development starts, without technical jargon or pressure to commit. Some SMEs have piloted a retail point of sale and accounting integration solution within days, which illustrates how long a proper pilot might take.
While Stripe and HitPay compete on payment rails and API depth, some pilots start from the till and the stock count, then connect the payment rail behind that, which is a different question to answer and often a faster one.
— Ronald
See how POSFlow handles a sale from product to payment
If the fee comparison above left you wanting to see a workflow rather than a rate card, that’s the more useful next step.
Our POSFlow product is built to keep the whole retail operation, stock, sale and payment, in one view, rather than stitching together a separate gateway, terminal and spreadsheet. You can run a sample sale from product to payment yourself to see how reconciliation actually looks before you decide anything.
A demo with us typically covers:
- A walk-through of your current sale-to-reconciliation steps, so we understand where time is lost.
- A live run of a sample sale through POSFlow, from stock to payment confirmation.
- A clear, jargon-free view of what an adapted or custom build would cost, if POSFlow isn’t the right fit.
If your business runs more on queues, events, leads or pricing than retail checkout, our QueueFlow, EventFlow, PriceFlow and LeadsFlow product lines cover those workflows, or you can browse everything we build at FlowLab.
FAQ
Which is better, PayMongo or HitPay?
PayMongo is built primarily for the Philippines market, while HitPay focuses on Singapore and wider APAC merchants, so the better fit depends on where you trade. For a Singapore SME taking local PayNow, QR and card payments, HitPay’s regional coverage is the more relevant comparison point.
What is Stripe’s biggest competitor?
Stripe competes with several global and regional payment processors, and in Singapore specifically, HitPay is the most commonly cited local alternative because of its full-stack, APAC-focused product. The better comparison depends on whether you need Stripe’s developer-first API depth or a bundled local platform.
Where is HitPay from?
HitPay is headquartered in Singapore and built as a full-stack payments platform for merchants across the APAC region, covering cards, PayNow/QR, digital wallets and B2B payments. Its Singapore entity is listed in the MAS Financial Institutions Directory with active status.
Does Stripe operate in Singapore?
Yes, Stripe Payments Singapore Pte. Ltd. holds an active Major Payment Institution licence under MAS, authorised for account issuance, merchant acquiring and cross-border transfers. You can verify current licence status directly on the MAS Financial Institutions Directory.
Does FlowLab offer a payment gateway like Stripe or HitPay?
We don’t operate a payment gateway ourselves. We build and adapt workflow-first products such as POSFlow that connect to payment rails, so you still choose a MAS-licensed provider for processing while we focus on the stock, sale and reconciliation layer around it.
Sources
Licence status can change, so always confirm current standing directly rather than relying on a single article. Start with the MAS Financial Institutions Directory entry for the specific legal entity you would be contracting with before signing any agreement.
- Financial Institutions Directory — Stripe Payments Singapore Pte. Ltd.
- Capitalmarkets
- HitPay — Y Combinator company profile
- What an online payment gateway is and how to choose one | Forbes